AI Infrastructure
The AI Utility Surcharge and Why Households May Pay for Grid Expansion
Record Labor Day fuel prices show why a cost seen every day can quickly shape the national...
America needs more electricity, fuel, transmission, and infrastructure as AI and industry raise demand, but when supply cannot keep pace, households face higher bills, weaker reliability, and greater exposure to global energy shocks.
America’s energy system is entering a period of rising demand. Artificial intelligence, data centers, manufacturing, electrification, and population growth are requiring more power from a grid that can take years to expand. At the same time, oil markets remain vulnerable to overseas disruptions, renewable supply chains depend heavily on foreign production, and major energy projects can spend years waiting for permits or surviving legal challenges. When supply and infrastructure fail to keep pace, the consequences reach household budgets through higher utility bills, fuel costs, and reliability risks. The central challenge is not choosing one energy source over another. It is building enough dependable supply, moving it where needed, and deciding fairly who pays for the infrastructure required to support growth.
The first energy challenge created by artificial intelligence is not simply producing more electricity. It is deciding who pays when exceptionally large new customers require the grid to expand. A major data center can consume as much electricity as 100,000 households, while the largest facilities could use up to 20 times that amount, meaning one project can create demand on a scale that local power systems were not originally built to serve.
That pressure is growing quickly. Data-center electricity demand increased nearly 150% between 2014 and 2022, and one high-growth scenario projects another 338% increase by 2030. The same analysis says new data-center forecasts contributed to more than $9 billion in additional capacity costs in a recent Mid-Atlantic power-market auction, showing how future demand can affect system costs before every planned facility is even operating.
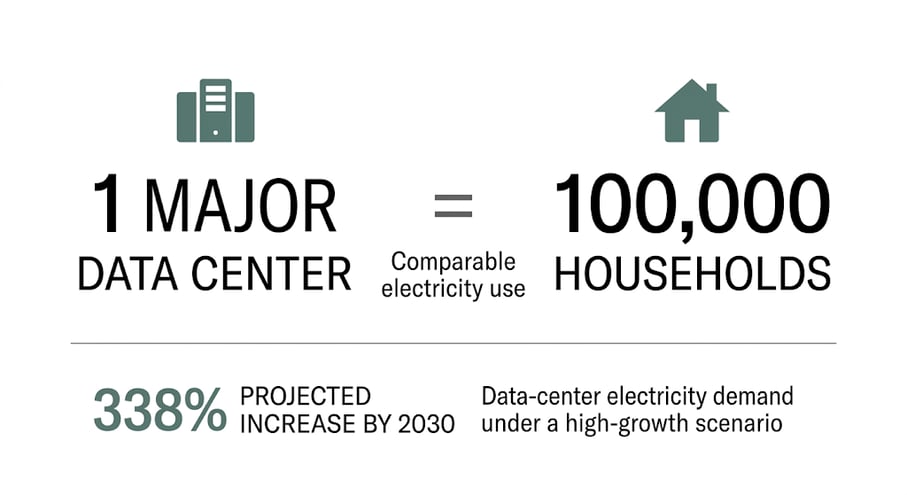
One major data center can rival 100,000 homes in power use. Created via Gemini.
Those costs can reach households because utilities recover the expense of building and maintaining the electricity system through customer rates. Transmission, the high-voltage network that moves electricity across long distances, accounts for about 12% of a typical electric bill, while distribution, the local wires and equipment delivering power to homes, accounts for about 25%. Not every new line or substation exists because of data centers, but when unusually large customers trigger new infrastructure, regulators must decide how much of that expense belongs to those customers and how much is shared more broadly.
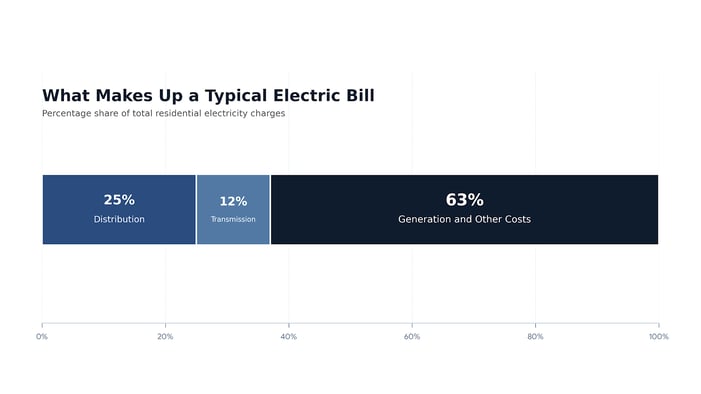
Transmission and distribution make up over a third of bills, Created via Gemini
The affordability stakes are higher because many households already struggle with utility costs. The analysis cited in the source found roughly 1 in 6 households behind on utility bills, while some low- and moderate-income households spend as much as 10% of their income on energy. It also projects residential electricity rates could rise nearly 18% over the period it examines, although that is a projection rather than a guaranteed nationwide increase and actual bills will vary by state, utility, and household usage.
A proposed $17 billion data-center campus in Georgia shows how quickly the scale of one project can become a local infrastructure question. The planned site covers about 4.34 million square feet, an area described in the source as roughly 606 football fields, while debate around the project has included energy, water, traffic, and transmission needs. The developer says the site was selected near existing power infrastructure, illustrating why project-specific studies matter before assuming that every large facility will create the same costs for surrounding customers.
One policy response is to require unusually large electricity users to carry more of the costs they create. Options described in the source include special utility rates, minimum payments, infrastructure deposits, and charges tied to consumption, while one proposed national affordability plan estimates that residential rate relief could prevent $129 billion in increases over 4 years and save the average household about $921. Those savings are estimates from a policy proposal, not an enacted benefit, and any fair-share system would also have to avoid discouraging useful investment or pushing facilities toward less transparent off-grid power arrangements.
Who pays for expansion is only the first part of the energy problem. Even if large users cover more of their own infrastructure costs, the grid still has to produce enough dependable electricity when homes, businesses, factories, and data centers all need power at the same time. That leads to the next question: when supply becomes tight, should flexible data centers lose power before households do?
America’s electricity system must do more than generate enough power over the course of a year. It must have enough dependable capacity available at the exact moments when demand peaks, especially during extreme heat, severe cold, or unexpected equipment failures. PJM Interconnection, which coordinates the regional high-voltage grid across 13 states and Washington, D.C., serves about 67 million people, making its experience an important test of how rapidly growing electricity demand could affect reliability.
Very large electricity users could add about 70 gigawatts of demand by 2038 across the PJM Interconnection region, with data centers expected to account for most of that projected growth. At the same time, PJM Interconnection’s latest capacity auction, the market used to secure enough future power resources to meet expected demand, fell about 6.8 gigawatts short of its reliability requirement. The figures measure different things, but together they show the challenge clearly: substantial new demand is projected while the regional system is already having difficulty securing all the dependable capacity it says it needs.
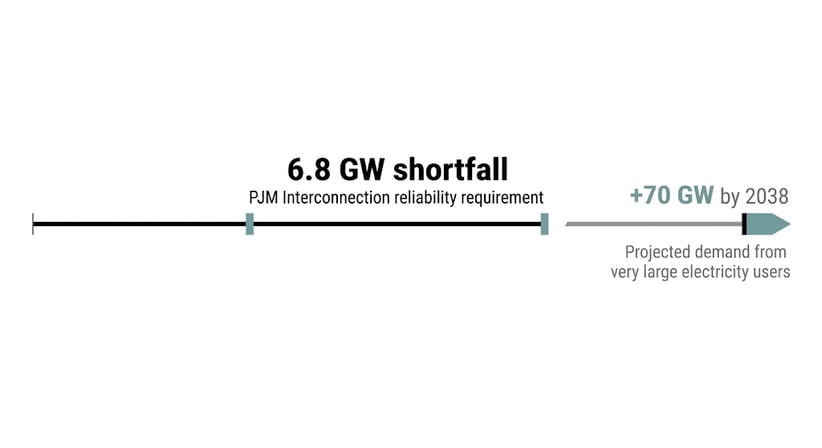
PJM Interconnection faces a reliability gap as demand rises. Created via Gemini.
When available electricity supply cannot meet demand, grid operators need ways to reduce consumption before the imbalance causes uncontrolled outages. One option is curtailment, which means temporarily reducing or stopping electricity use at selected facilities to protect the wider system. A large data center may be able to reduce computing activity, shift some operations to backup generation, or temporarily disconnect equipment in ways that ordinary households generally cannot.
The pressure became visible during extreme heat in July, when PJM Interconnection recorded instantaneous demand of about 162,700 megawatts on July 2. Roughly 6,000 megawatts of demand response helped suppress the measured peak by having participating customers reduce electricity consumption when called upon. Utilities were also prepared to curtail large customers with backup generation, although the system ultimately avoided widespread service interruptions.
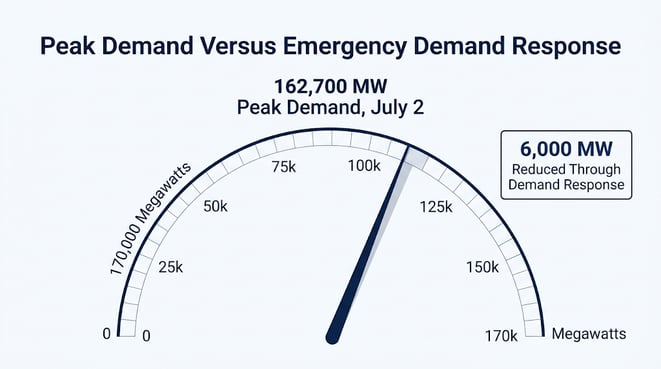
Demand response helped the grid survive a record July peak, Created via Gemini
The economic signal was just as important. PJM Interconnection’s capacity auction reached a price cap of $325 per megawatt-day and still failed to secure enough resources to satisfy its reliability requirement. Higher prices therefore did not immediately produce enough dependable capacity because power plants, transmission lines, substations, and other infrastructure require years of planning, permitting, financing, and construction.
PJM Interconnection is now considering rules that would improve visibility into exceptionally large electricity users and allow some new facilities to connect sooner if they accept interruption during periods of system stress. Proposals affecting the regional wholesale power system would operate within rules overseen by the Federal Energy Regulatory Commission (FERC), the federal agency responsible for interstate electricity transmission and wholesale power markets. The underlying tradeoff is whether customers seeking unusually large amounts of electricity should receive the same guarantee of uninterrupted service if they connect before enough supporting generation has been added.
For households, that distinction matters because most families cannot move their essential electricity use somewhere else during an emergency. Refrigeration, heating and cooling, medical equipment, communications, and many basic household functions depend on continuous service, while small businesses can lose payment systems, refrigeration, or production capacity during outages. Curtailment rules could therefore protect residential customers by requiring large flexible users to reduce demand first, while still recognizing that some data centers support essential financial, communications, health, and government services.
Reliability rules can help operators manage periods of limited supply, but they cannot eliminate the need for adequate energy production. The same constraint appears in oil markets, where even record U.S. production cannot immediately replace a major disruption in global supply. Understanding those limits is the next part of America’s energy challenge.
The United States produces more oil than at any earlier point in its history, but high domestic production does not make American households immune from disruptions elsewhere in the world. U.S. crude output reached about 13.6 million barrels per day in 2025, according to figures cited from the U.S. Energy Information Administration. Yet oil remains a global market, so a large disruption overseas can raise prices faster than American producers can add new supply.
That limitation comes from both timing and scale. New shale production generally requires about 6 to 9 months to bring online even under favorable conditions, while a Dallas Federal Reserve survey found 70% of shale executives expected production to increase over the following two years but 43% expected gains of no more than 250,000 barrels per day. Those numbers show why domestic producers can respond to sustained higher prices without being able to replace a major international supply loss within days or weeks.
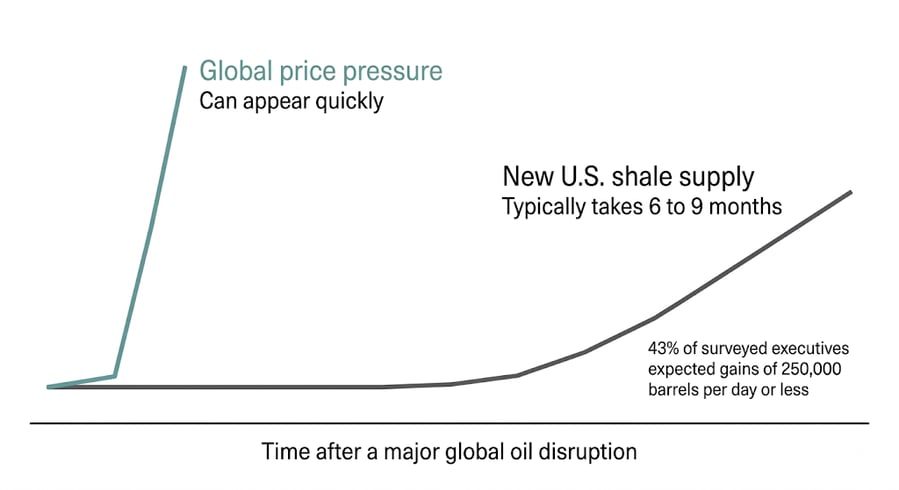
New shale supply takes months to reach the market. Created via Gemini.
The scale becomes clearer during a major disruption in the Persian Gulf. The source cites an estimate that regional crude production fell by more than half from pre-conflict levels after shipping through the Strait of Hormuz was disrupted. Against a loss measured in millions of barrels per day, a potential U.S. shale increase of a few hundred thousand barrels per day would narrow only a fraction of the gap.
American producers also have economic reasons not to respond to every price spike with an immediate drilling surge. Years of investor pressure following periods of costly overproduction have pushed shale companies toward what the industry calls capital discipline, meaning companies place greater emphasis on controlling spending and returning cash to shareholders rather than maximizing output at any price. Production can also be constrained by drilling rigs, specialized crews, equipment, pipeline capacity, and supply-chain delays, so higher oil prices alone do not guarantee an immediate increase in barrels.
Longer-term production trends add another constraint. The source says the U.S. Energy Information Administration expects domestic crude production to plateau before declining modestly, while longer-range projections suggest output could peak before the end of the decade. The Permian Basin, which the article says supplies nearly half of U.S. crude oil, remains the country's most important production region, but its highest-quality drilling locations are finite.
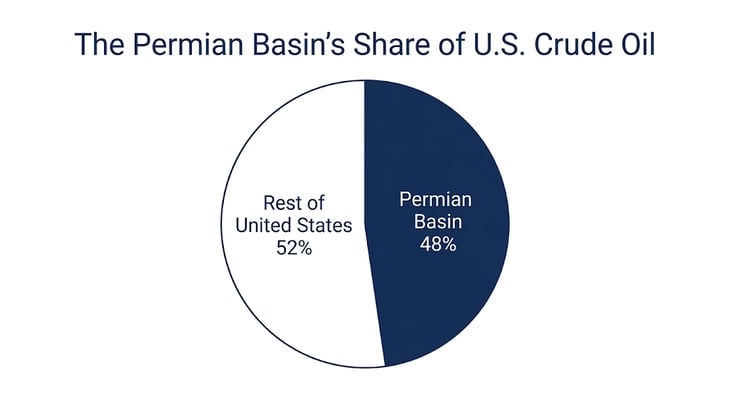
One region supplies nearly half of all domestic crude oil.Created via Gemini
For households, the important distinction is between energy production and energy insulation. Producing large amounts of oil at home gives the United States more protection than relying heavily on imports, but gasoline prices still reflect global crude prices, shipping conditions, refinery capacity, and expectations about future supply. A disruption large enough to move the global market can therefore raise transportation and delivery costs even when American wells continue producing at record levels.
The policy challenge is not simply telling producers to drill more whenever prices rise. Maintaining energy security requires sufficient domestic production, transportation capacity, investment incentives, and access to global supplies that can absorb unexpected losses elsewhere. It also requires recognizing that additional American barrels arrive on an industrial timeline, while an international crisis can affect oil prices almost immediately.
That difference in timing helps explain another frustrating experience for consumers. Global oil prices can rise quickly when supplies are disrupted, but they may take much longer to normalize after a crisis begins to ease because tankers, ports, refineries, and distribution networks still have to recover. That delayed path from global supply to the neighborhood gas station is the next part of the energy story.
America may produce large amounts of oil at home, but gasoline and diesel prices still depend on a global system of producers, shipping routes, ports, refineries, pipelines, and fuel terminals. When one part of that system is disrupted, prices can respond quickly because markets immediately account for the possibility of less available supply. Restoring normal conditions takes longer because the physical movement and processing of oil cannot recover at the speed of a financial market.
The 2026 disruption in the Strait of Hormuz showed how large those physical backlogs can become. More than 1,500 tankers were reported waiting to transit or unload, while some recovery scenarios expected traffic initially to return to only 60% to 70% of pre-disruption levels. Analysts cited in the source estimated that restoring full tanker transit capacity could take up to 3 months, demonstrating why reopening an important shipping route does not immediately restore the flow of fuel.
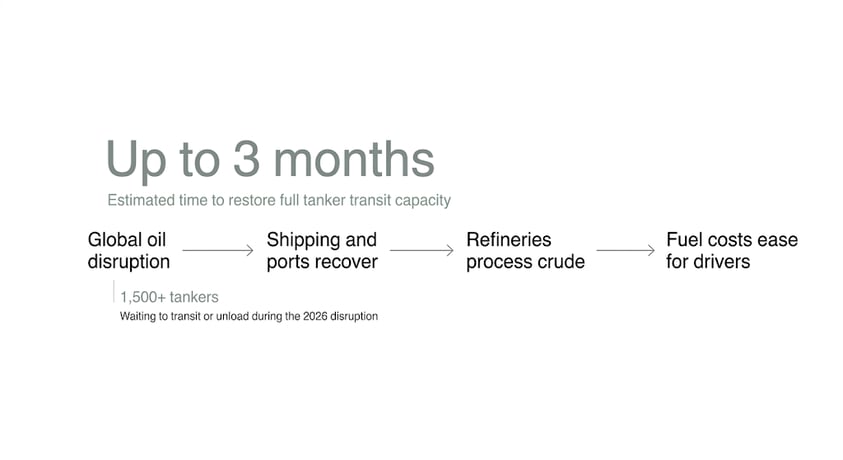
Oil-market disruptions can outlast the event that caused them. Created via Gemini.
Shipping is only the first stage. Crude oil that begins moving again must reach a port, travel to a refinery, be processed into gasoline or diesel, and then move through storage and distribution networks before reaching local stations. Congestion or reduced operations at any stage can extend the period between an improvement in global conditions and meaningful relief for consumers.
Refineries create another important constraint because additional crude supply does not automatically become additional gasoline. Facilities that reduced production during a shortage may need time to increase operations, while accumulated backlogs can compete for available processing capacity. This helps explain why the physical energy system can continue transmitting the effects of a disruption after the geopolitical event itself has moved out of the headlines.
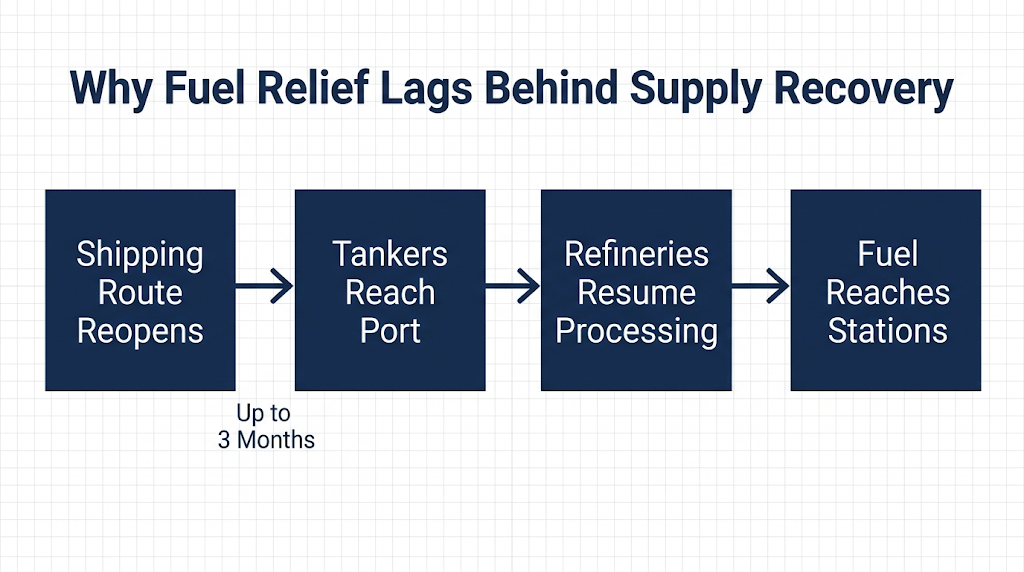
Fuel relief always takes longer than the shipping route reopening.Created via Gemini
The lesson for households is broader than one conflict or one shipping route. Gasoline prices reflect crude costs, transportation, refining capacity, inventories, and expectations about future supply, so improvements in one part of the system may not immediately reduce the final retail price. Families can continue feeling the effects through commuting and transportation costs, while businesses can face higher expenses for freight and deliveries that eventually influence the prices of other goods.
That is why energy security depends on more than producing enough crude oil. The United States also needs transportation routes, refinery capacity, inventories, and infrastructure capable of absorbing disruptions without allowing a temporary shortage to become a prolonged affordability problem. A resilient energy system shortens the distance between restoring supply and restoring stability for consumers.
The same resilience question appears in other parts of America’s energy system. Renewable power can diversify domestic electricity supply, but the equipment behind that expansion can depend heavily on overseas manufacturing. That creates a different question about energy security: how much of America’s future power infrastructure should depend on foreign supply chains?
Solar power can add electricity without relying on the same fuel markets that expose households to oil and natural-gas disruptions, but building more solar capacity creates a different kind of dependence. Chinese companies account for about 80% of the global solar supply chain, according to Reuters, giving one manufacturing network enormous influence over the equipment used to expand power generation elsewhere. That concentration means America's ability to add solar power depends not only on how many projects it approves, but also on where the cells, wafers, and other components are actually produced.
The scale of that dependence is substantial. U.S. Department of Commerce data examined solar-cell imports from Cambodia, Malaysia, Thailand, and Vietnam, which together supplied 36.4 gigawatts of imports worth $11.9 billion in 2023. Commerce later announced final trade determinations involving those 4 countries in 2025, although those figures cover solar-cell imports broadly and do not measure blue wafers specifically.
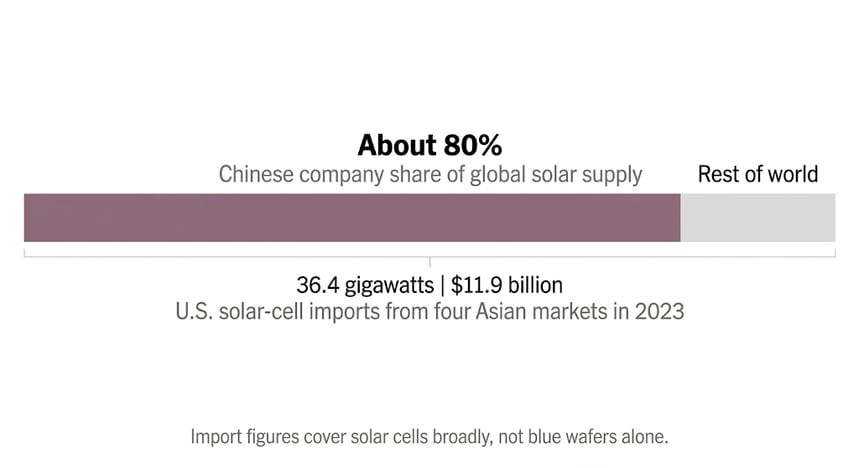
Foreign supply remains central to America’s solar expansion. Created via Gemini.
Trade policy is intended to reduce that dependence by protecting domestic manufacturers from unfairly priced or subsidized imports. Solar cells made in China and 8 other Asian countries face anti-dumping or countervailing duties under existing U.S. trade rules, but changing where a product is shipped or how far it is processed can complicate enforcement. The current blue-wafer dispute illustrates that problem because lawmakers allege some partially finished products receive limited processing in the United States before companies seek treatment normally associated with domestic manufacturing.
A blue wafer sits between an unfinished silicon wafer and a completed solar cell. Under the disputed arrangement, a partly processed product can arrive from overseas, receive final manufacturing steps in the United States, and potentially interact differently with import duties and Section 45X manufacturing tax credits. The important qualification is that the available evidence does not establish a verified dollar amount of improperly claimed credits, so the issue should be understood as an enforcement and classification dispute rather than proof of a multibillion-dollar fraud.
That distinction matters because federal policy is trying to accomplish 2 goals at once: keep solar equipment affordable enough to expand electricity supply and create more genuine manufacturing capacity inside the United States. Stronger origin rules could reduce competition from subsidized imports and make federal incentives more likely to reward substantial domestic production, but restricting inexpensive foreign inputs can also raise solar-cell and module costs. With 80% of global solar supply linked to Chinese companies, replacing foreign capacity quickly would require more than changing a tariff classification.
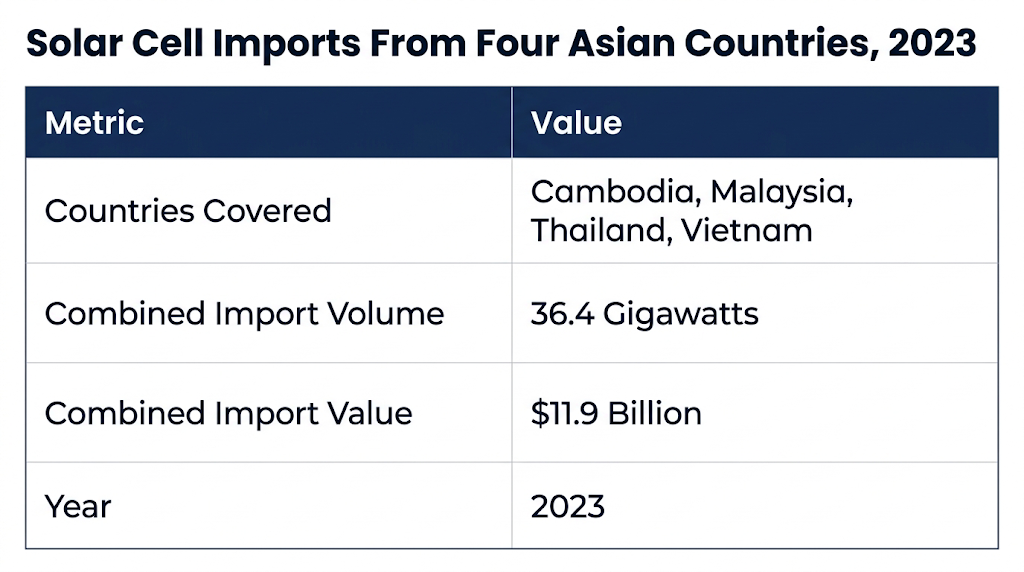
Four countries supplied most solar imports before trade rules changed, Created via Gemini
The household tradeoff therefore runs in both directions. Cheaper imported components can reduce the cost of building solar projects in the near term, while greater domestic production can reduce long-term exposure to foreign supply disruptions and trade disputes. The $11.9 billion of imports examined across 4 Asian markets shows why either choice has consequences at scale. Tighter rules may increase some project costs today, while weak enforcement may leave future American electricity expansion dependent on supply chains the country does not control.
A durable solar strategy must therefore measure success by more than the number of panels installed. America needs enough affordable equipment to add generation while ensuring that manufacturing incentives actually produce meaningful domestic capacity rather than rewarding only the final step of an overseas production chain. That balance becomes even more important when new energy projects of every type face another obstacle: the years of permitting, financing, and legal review required before new supply can reach the grid.
America can have abundant energy resources and still struggle to deliver affordable power if the infrastructure needed to move that energy takes too long to build. The National Environmental Policy Act (NEPA), enacted in 1970, requires federal agencies to consider environmental effects before major federal actions move forward. More than 50 years later, the central policy question is how to preserve meaningful environmental review without allowing procedural uncertainty to add years of financing and construction costs to projects consumers ultimately depend on.
The 303-mile Mountain Valley Pipeline shows how large those costs can become. When construction began in February 2018, the natural-gas project was expected to cost about $3.5 billion and enter service later that year, but repeated regulatory and court disputes interrupted work before the pipeline finally entered service in June 2024. By completion, Reuters reported that the estimated project cost had climbed to $7.85 billion, more than twice its original estimate.
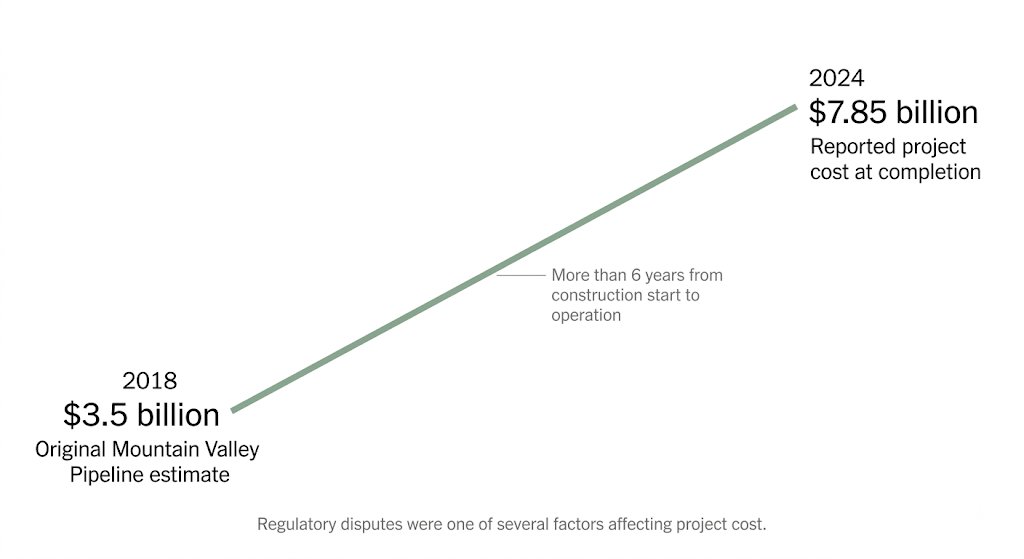
Years of delay can turn infrastructure into a much costlier project. Created via Gemini.
The additional $4.35 billion between the original estimate and final reported cost cannot automatically be attributed entirely to permitting, because major construction projects can also face inflation, engineering changes, labor costs, and other pressures. Still, the project spent more than 6 years moving from the start of construction to operation while regulatory and court disputes repeatedly interrupted work. Every additional period of uncertainty can increase borrowing costs, extend contracts, delay revenue, and make investors demand greater compensation for committing capital.
Those financing pressures matter because energy infrastructure is unusually capital intensive. Pipelines, transmission lines, nuclear facilities, geothermal projects, and grid upgrades can require large investments years before customers receive the first unit of energy from them, so even a project ultimately approved can become substantially more expensive during a prolonged review. The Mountain Valley Pipeline's rise from about $3.5 billion to $7.85 billion demonstrates the scale such cost escalation can reach, even though permitting was only one of several forces affecting the final price.
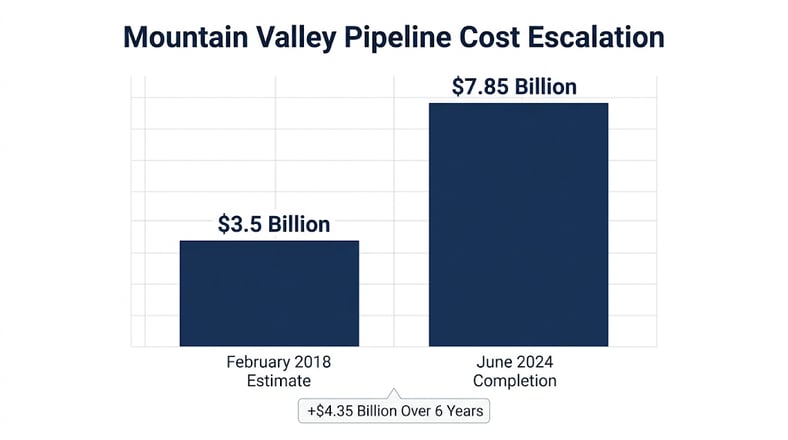
Mountain Valley Pipeline costs doubled across six years of delays.
The household consequence appears when infrastructure shortages leave regions dependent on more expensive alternatives. The source points to New England, where constraints on natural-gas pipeline capacity can contribute to reliance on fuel oil during periods of high demand even though major domestic gas resources are located relatively nearby. The lesson is not that every proposed pipeline should be approved, but that blocking or delaying supply infrastructure can carry an economic cost that must be weighed alongside the environmental and community costs considered during review.
Federal policy has begun focusing on whether some reviews can be completed more efficiently without eliminating environmental safeguards. In April 2026, the Council on Environmental Quality issued guidance on the use of categorical exclusions, which allow agencies to use a simpler review process for categories of actions that normally do not have significant environmental effects. The approach aims to reserve more extensive review for projects that genuinely require it rather than treating every federal action as though it carries the same environmental risk.
Permitting reform has also attracted lawmakers from both parties because delays affect several competing energy priorities. The Build America Caucus described in the source includes 20 Democrats and 20 Republicans and identifies energy permitting and transmission reform among its priorities. That alignment reflects a practical reality: fossil-fuel infrastructure, renewable generation, transmission lines, housing, and other major projects can all become more expensive when approvals remain uncertain for years.
The durable policy challenge is therefore not choosing between environmental review and construction. It is designing a system in which serious environmental risks receive meaningful scrutiny while projects that satisfy the rules can move toward financing and completion within predictable timelines. Faster approval alone, however, does not solve the entire problem if a project can still be stopped after receiving its permits and committing substantial capital, which is the next infrastructure risk this page examines.
Getting an energy project approved is not enough if investors cannot rely on that approval after construction begins. Large infrastructure projects require years of planning and substantial capital before they produce revenue, so the possibility of a late regulatory reversal becomes a financial risk that developers and lenders must price in from the start. The proposed Fighting for Reliable Energy and Ending Doubt for Open Markets Act, H.R. 7329, introduced in February 2026, reflects this concern by proposing limits on federal actions that halt fully permitted projects and creating tools intended to reduce late-stage permitting risk.
Revolution Wind demonstrates how significant that risk can become after construction is already advanced. The 704-megawatt offshore wind project was reported to be about 80% complete, with all offshore foundations installed and 45 of 65 turbines already in place, when federal officials issued a stop-work order in August 2025. Whatever the merits of the underlying national-security review, halting a project after that much capital has been committed illustrates why investors care not only about obtaining a permit, but also about whether that permit remains dependable.
Late reversals can put substantial completed investment at risk. Created via Gemini.
The same uncertainty can affect conventional energy infrastructure. A Transco natural-gas expansion received approval from the Federal Energy Regulatory Commission in January 2023 and was designed to add 829,000 dekatherms per day of pipeline capacity across Pennsylvania, New Jersey, and Maryland. A federal appeals court vacated that approval in July 2024, before the certificate was reinstated in January 2025, and Reuters reported that the project was designed to provide enough gas to serve the annual needs of about 4.4 million homes.
These cases do not mean that every permit should become impossible to challenge. Courts and regulators still need authority to correct legal errors, address legitimate safety concerns, and enforce environmental requirements. The economic problem arises when projects with hundreds of megawatts of planned capacity or infrastructure serving millions of customers remain exposed to substantial uncertainty after years of review and investment, because that uncertainty can raise financing costs for the next project even if the current one eventually moves forward.
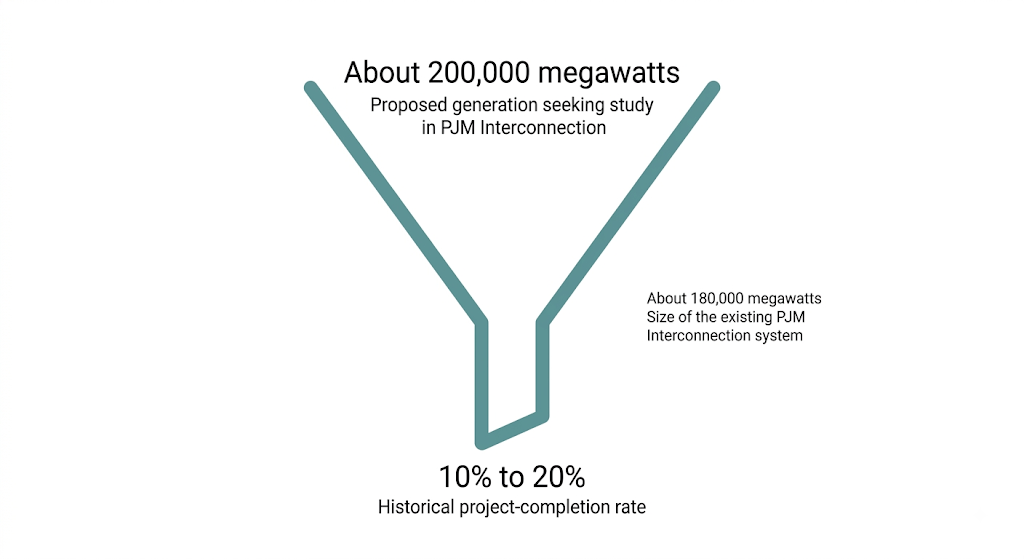
The scale of America's unfinished power pipeline makes that distinction especially important. PJM Interconnection operates a regional system of roughly 180,000 megawatts, while about 200,000 megawatts of proposed generation has been seeking study for connection to its grid. Yet the source reports historical project-completion rates of only about 10% to 20%, showing why a large development queue should not be mistaken for dependable future electricity supply.
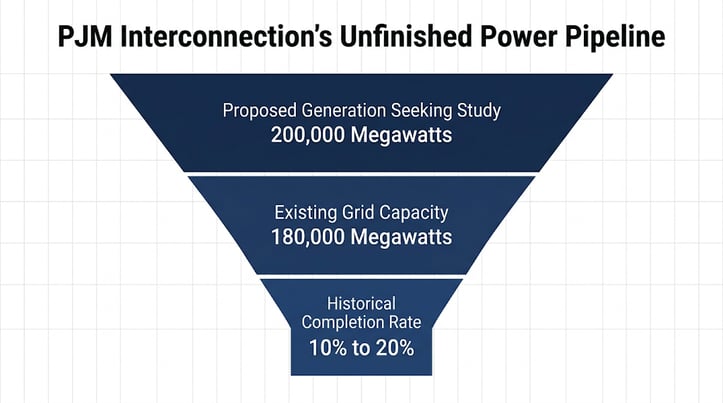
Most queued power projects rarely reach the electricity grid fully.Created via Gemini
A proposed power plant does not help consumers simply because it appears in a queue. It must complete engineering studies, obtain permits, secure financing, connect to transmission, survive legal review, and enter commercial operation before any of its megawatts can serve households or businesses. If only 10% to 20% of proposed projects historically reach completion in a region facing roughly 200,000 megawatts of queued capacity, policies that improve the probability of viable projects reaching operation can matter as much as policies encouraging developers to submit more proposals.
The household consequence is ultimately a question of supply and financing. When fewer planned projects become operating projects, utilities have fewer resources available to meet rising demand, while projects that do proceed may carry higher financing costs if investors expect approvals to remain vulnerable. Permit certainty cannot guarantee lower electricity bills, but a system capable of turning lawful approvals into completed infrastructure can reduce one source of unnecessary cost and improve the odds that planned energy supply actually reaches consumers.
The broader lesson is that America's energy challenge is not solved when policymakers announce new projects or developers file applications. Capacity matters only when infrastructure is financed, built, connected, and operating. That principle also applies to data centers, where new power investment can bring additional infrastructure into communities, including fiber networks, but those local benefits depend heavily on how projects are planned.
Data centers show how decisions about electricity supply can reshape infrastructure far beyond the power grid. As available electricity becomes harder to secure in established technology hubs, developers are increasingly considering locations where power is available even if communications networks are less developed. The Badger Institute reported that some artificial intelligence applications may perform best within about 100 miles or 3 milliseconds of a facility, while especially time-sensitive uses may require responses below 1 millisecond.
Moving computing into new locations requires much larger fiber connections than many communities have historically needed. Broadband Breakfast reported that 12 fibers was once considered a large cable, while major new data-center routes now routinely contain 1,728 fibers. Some facilities request conduits containing 432 or 864 fibers and at least 4 separate entrances, showing how power-driven development can also expand the physical communications network around a site.
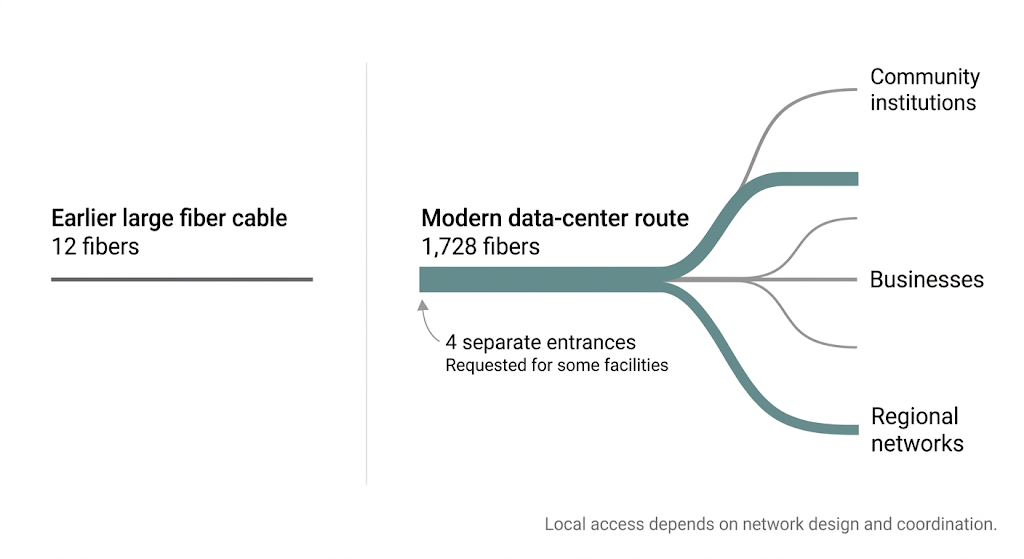
Power availability can pull major fiber investment into new regions. Created via Gemini.
Building those networks can be especially difficult outside major cities. Broadband Breakfast reported that metropolitan connections may take about 2 to 2.5 years, compared with 3 to 5 years for rural routes because they can cross more properties, jurisdictions, and permitting systems. One project discussed in the source stretched 693 miles and required 74 separate permitting processes, showing how locating computing near available electricity can trigger a much broader infrastructure build.
More fiber near a community does not automatically mean faster or cheaper household internet. Even a route containing 1,728 fibers can pass homes, farms, schools, hospitals, and businesses without providing usable local connections if it was designed only for a private data-center campus. The opportunity is that these routes can bring high-capacity infrastructure closer to communities and improve network redundancy, reducing one barrier that previously made expansion uneconomical.
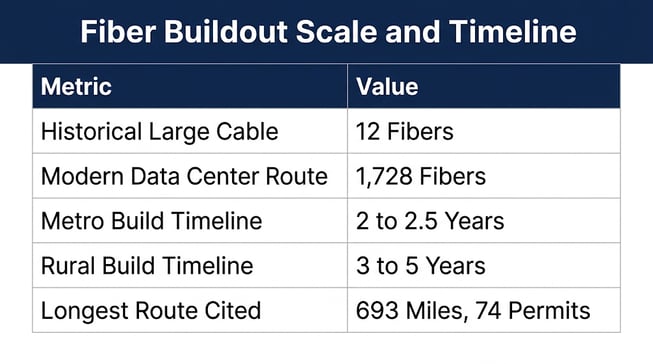
Fiber routes grew far larger while rural buildouts still lag.Created via Gemini
Local governments therefore have the greatest leverage before routes and permits are finalized. Next City has argued that municipalities can overlook broadband when negotiating data-center projects even though facilities may require multiple independent fiber routes, including as many as 4 separate entrances in examples cited by the source. Bringing internet providers, schools, hospitals, businesses, and network specialists into those discussions can help communities determine where connection points, spare capacity, workforce commitments, or other measurable benefits are realistic.
Rural communities may have the largest potential opening because long distances make broadband infrastructure expensive to finance. A data center capable of supporting a fiber project stretching hundreds of miles can become an anchor customer large enough to make a new regional route economically possible, although it still does not solve the final connection from that network to individual homes. With rural routes taking as long as 3 to 5 years, communities have the strongest opportunity to shape those investments when broadband planning begins alongside energy, zoning, and permitting decisions.
The broader energy lesson is that major new electricity users affect more than generation and utility bills. Their search for available power can determine where computing investment goes, while fiber requirements that have grown from examples of 12 fibers to 1,728 fibers can bring substantial communications infrastructure with it. America’s energy future will therefore depend not only on producing enough electricity, but also on whether communities convert the infrastructure surrounding new demand into durable local economic value.
America’s energy challenge is increasingly a problem of building and delivering enough dependable supply, not simply identifying new sources of power. Data centers and industrial growth can require major additions to generation, transmission, and local grid infrastructure, while oil disruptions can still reach American consumers through global markets. The question is whether new demand is matched by new capacity quickly enough, and whether the customers creating exceptional infrastructure needs pay an appropriate share of the cost.
More domestic energy does not automatically mean greater energy security. Oil still depends on shipping, refining, and distribution, while solar expansion relies heavily on overseas manufacturing networks. A stronger system needs multiple sources of supply, sufficient transportation and processing capacity, and domestic production that can reduce exposure when foreign markets or supply chains are disrupted.
The final constraint is execution. Proposed generation does not strengthen the grid until it is permitted, financed, connected, and operating, and infrastructure becomes more expensive when approvals take years or remain uncertain after construction begins. America’s energy future will depend on whether the country can turn rising demand into dependable supply without making households absorb costs created by delays, shortages, or poorly structured investment.
Record Labor Day fuel prices show why a cost seen every day can quickly shape the national...

Artificial intelligence may reduce demand for some knowledge jobs while creating an urgent need for...

America’s AI race now depends on the workers who build power, data centers, fiber, and trust.