AI and Automation
Blackout Priority and Whether Data Centers Should Be First to Lose Power
AI growth is testing whether households should remain protected when electricity supplies cannot...
The old path from college to office work is weakening as AI absorbs junior tasks, tech productivity pulls ahead, empty offices strain lenders, and data centers create demand for skilled workers across America.
The next American economy is already taking shape in places that do not always look connected. Young graduates are finding fewer entry points into office careers, while remote work is leaving commercial buildings under pressure and creating risks for lenders. At the same time, AI investment is increasing demand for data centers, electricity, transmission, construction, and skilled trades that software cannot provide on its own. Productivity gains are also concentrating heavily inside technology while many workers and smaller businesses feel less of the boom. Together, these changes show an economy reallocating work, capital, and opportunity. The challenge is whether workers, lenders, training systems, and communities can adjust quickly enough for new investment to spread opportunity instead of widening economic divides.
Artificial intelligence (AI) is beginning to change entry-level office work before many workers have a chance to build experience. Goldman Sachs Research estimates that about 300 million jobs globally are exposed to some degree of AI automation, although exposure does not mean those jobs will disappear. The immediate concern is agentic AI, meaning systems that can complete multi-step tasks with limited human direction, because those systems can perform parts of writing, research, coding, and customer support once assigned to junior employees.
Goldman Sachs Research also estimates that AI could eventually automate tasks representing about 25% of U.S. work hours. Its analysis projects that roughly 6% to 7% of workers could face displacement as adoption spreads, with entry-level knowledge workers among those facing the earliest pressure. These figures measure potential automation and displacement, not a prediction that 25% of American jobs will disappear.
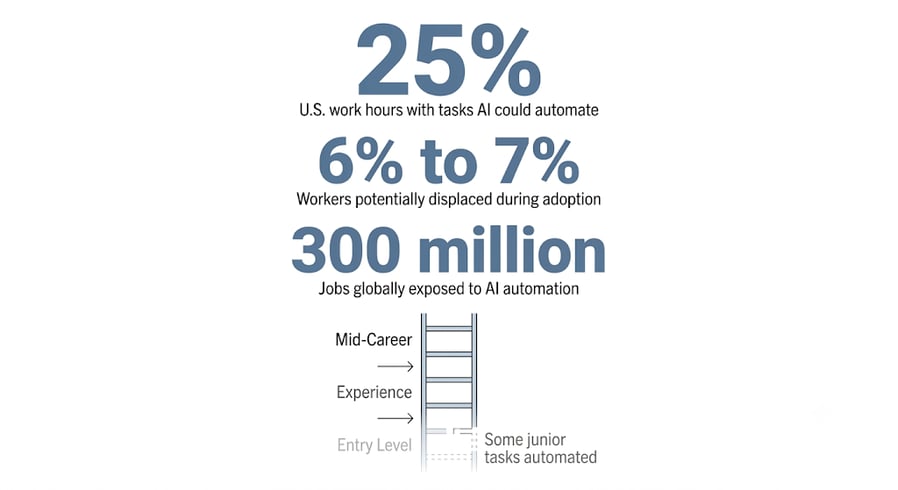
AI could automate junior tasks before workers gain experience. Created via Gemini.
Entry-level jobs have traditionally served as both paid work and professional training. The source describes the first 2 years of many knowledge careers as a period when junior workers develop capability through repeated assignments, supervision, mistakes, and feedback. If AI absorbs more of those basic tasks, employers may gain efficiency while reducing the opportunities through which inexperienced workers become experienced employees.
The pressure may be strongest for workers in their 20s and 30s entering knowledge and content roles. In a Fox Business discussion, a Goldman Sachs executive predicted wider use in 2026 of an approach known as “agent as a service,” where companies use specialized AI agents for work such as coding, finance, customer service, and design. That does not mean junior hiring will disappear, but it changes the calculation when software can complete some work previously assigned to a new employee.
The risk extends beyond individual hiring decisions. Goldman Sachs projects unemployment could rise to about 4.5% in 2026 if AI-related job losses arrive faster than its longer-term base case assumes. That is a forecast rather than a guaranteed outcome, but it shows why losing entry-level opportunities matters beyond one hiring cycle because workers who cannot enter a field have fewer chances to accumulate the experience required for higher-level jobs later.
At the same time, the economy is creating work in very different places. Data-center expansion has been associated with 216,000 additional construction jobs since 2022, while roughly 500,000 net new infrastructure jobs are estimated to be needed by 2030. Those opportunities do not automatically solve the entry-level problem because a displaced junior analyst, writer, or support worker cannot immediately become an electrician, construction specialist, or grid technician without retraining, making AI disruption a workforce-development problem as well as a technology story.
For many young Americans, earning a college degree no longer guarantees an easy first step into a career. More than 2 million students are graduating in 2026 into an entry-level market where a degree is becoming harder to convert into career-building work. Nearly 43% of U.S. college graduates ages 22 to 27 were underemployed in December 2025, meaning they were working in jobs that typically did not require a college degree, while recent-graduate unemployment stood at 5.7%, compared with 4.2% across the overall workforce.
Competition is also intensifying for the openings that remain. Entry-level job postings were down 35% since early 2023, while postings aimed specifically at new graduates fell 15% year over year and applications per role increased 30%. Fewer openings combined with more applicants mean graduates are competing harder just to reach the first stage of a professional career.
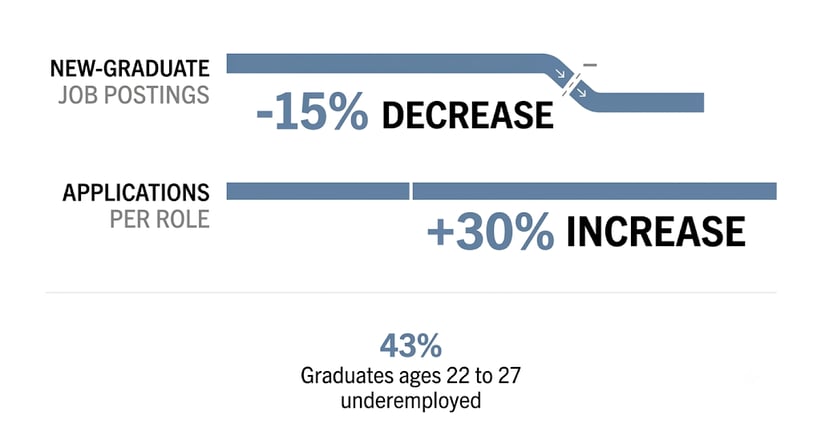
Fewer graduate openings are drawing more applications. Created via Gemini.
Money can provide some families with another way into that crowded market. Private career coaching described in the source can cost more than $50,000, while other intensive services charge above $30,000. Fortune reported families paying around $15,000 beginning as early as a student’s sophomore year, buying individualized preparation and attention that many households cannot afford.
The current difficulty should not be blamed entirely on artificial intelligence. Graduate underemployment has remained between roughly 38% and 45% for two decades, showing that many degree holders struggled to find college-level work long before the latest AI boom. What has intensified is the competition within that already difficult market: among 2025 graduates, 16% submitted more than 20 applications before receiving a single offer.
The traditional employment advantage attached to a college degree has also narrowed. The source cites Federal Reserve Bank of Cleveland findings showing that the unemployment gap between college and high school graduates fell from 3.8 percentage points in 2006 to 1.9 percentage points in 2025. A degree can still provide substantial long-term value, but those numbers suggest families should be more cautious about assuming that graduation will automatically lead to a quick professional start.
Some of the sharpest pressure is appearing in technology, once a major destination for new graduates seeking well-paid professional work. Labor-market analysis cited in the source found big technology companies hiring 25% fewer recent graduates than in 2023 and roughly 50% fewer than before the pandemic. Meanwhile, 51% of employers rated the 2025 to 2026 graduate market as fair or poor, while 89% of graduating seniors worried AI could replace entry-level roles, up from 64% the previous year.
For households, the consequences can last well beyond the first unsuccessful job application. A delayed career start means less time accumulating experience, earnings, savings, and the financial independence that supports later decisions such as moving out, paying down education costs, or forming a household. When some families can spend $15,000 to more than $50,000 for additional career help while others compete without that support, a difficult entry-level market can also deepen the inequality surrounding who gets a strong start.
The shift away from full-time office work is leaving a financial problem behind even after workers have adjusted to new routines. The delinquency rate for office loans packaged into commercial mortgage-backed securities (CMBS) rose from roughly 1.60% in mid-2022 to a record 12.34% in January 2026, according to Trepp. Falling demand for office space matters because buildings financed at older valuations can become much harder to refinance when occupancy is weaker and borrowing costs are higher.
The next pressure point is the large volume of loans reaching the end of their financing terms. About $875 billion in commercial mortgages are scheduled to mature during 2026, although that figure covers commercial property broadly and should not be read as $875 billion of troubled office debt. Among office CMBS loans that had already matured before 2026 and were still outstanding, more than 83% were delinquent, showing how refinancing problems can turn into missed payments when borrowers cannot repay or replace an expiring loan.
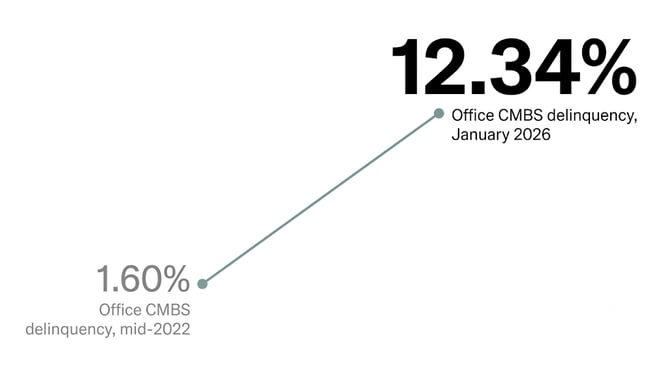
Office CMBS delinquency climbed sharply after 2022. Created via Gemini.
The stress is concentrated rather than uniform across every commercial property and every lender. The Mortgage Bankers Association reported that overall commercial mortgage delinquency rose from 3.86% in Q4 2025 to 4.02% in Q1 2026, while CMBS loans had a higher delinquency rate of 5.21%. Offices remain among the most difficult property types, which makes lenders with heavier office exposure more vulnerable than banks with more diversified loan portfolios.
That distinction matters especially for regional and community banks because many hold significant amounts of commercial real estate (CRE) lending relative to their size. Regulators flag a CRE concentration above 300% of a bank’s total equity for heightened oversight, giving depositors and investors one way to judge whether a lender has unusually heavy exposure. A bank above that threshold is not automatically in trouble, but the number becomes more important when office delinquencies are already above 12% in the CMBS market.
The banking risk also depends on what happens when an office loan reaches maturity. A building financed during 2018 to 2021 may have been valued under very different occupancy and interest-rate conditions, making a new loan harder to secure at the old amount. When refinancing fails, a lender can be left with a property worth less than the balance supporting the original loan, turning an empty-office problem into a balance-sheet problem.
For households, that does not mean every regional bank is facing a crisis or that depositors should assume their money is unsafe. Deposits at institutions insured by the Federal Deposit Insurance Corporation (FDIC) are generally protected up to $250,000 per depositor, per ownership category, while banks with diversified portfolios may have far less exposure to troubled offices. The practical lesson is narrower: a workplace shift that began with remote work can eventually reach local lenders, credit conditions, and communities when large commercial debts cannot be refinanced.
The office market may also have further adjustment ahead. Trepp estimated that office CMBS delinquency could peak between 12% and 13% before the existing pipeline of distressed loans clears, making that a forecast rather than a guaranteed outcome. With $875 billion in commercial mortgages maturing during 2026, the pace of refinancing and loan resolution will help determine whether office stress remains concentrated or spreads further through lenders exposed to commercial property.
A technology boom can lift markets without improving the economy evenly for everyone living inside it. Since 1998, productivity in the information sector has risen 322%, compared with only 32% outside the technology sector, according to the productivity analysis underlying this section. That gap helps explain why workers and businesses can hear that the economy is becoming more productive while seeing much less change in their own industries.
The divide has become especially visible since October 2022. Information-sector profits increased nearly 90%, while profits across the rest of the S&P 500 rose only about 10% over the same period. The same analysis calculates annualized productivity growth since 1998 at 5.48% in the information sector versus 1.21% across the rest of the economy, suggesting that technology-led efficiency gains have remained unusually concentrated.
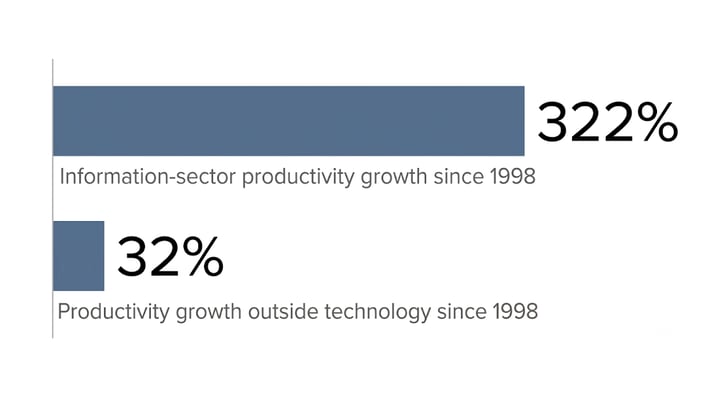
Technology productivity has far outpaced the rest. Created via Gemini.
Higher productivity numbers also need careful interpretation because producing more with fewer workers can temporarily look like greater efficiency. Information-sector productivity rose nearly 12% in 2025, while employment in that sector declined 1.8% and broader job growth was described in the analysis as essentially flat. Productivity across private nonfarm businesses also rose 4.9% in Q3 2025, but the underlying productivity discussion says it remains unclear how much of that increase came from artificial intelligence and how much came from companies operating with fewer workers.
Technology has also become large enough to influence headline economic performance more heavily than it did in earlier decades. A March 2026 productivity analysis estimates that newer technology-driven companies now account for more than 20% of changes in gross domestic product (GDP), compared with roughly 8% in the 1980s. Gross domestic product (GDP) measures the value of goods and services produced across the economy, so faster growth in a large technology sector can make national figures look strong even when conditions elsewhere are much weaker.
That difference matters because a productivity boom becomes more economically meaningful when its benefits spread beyond the industries producing the technology. The analysis argues that the information sector has been pulling away from the rest of the economy since 2022, rather than lifting productivity everywhere at the same pace. If that pattern persists, workers and smaller businesses outside technology may continue experiencing an economy that feels much weaker than the headline performance of major technology companies suggests.
The current productivity numbers therefore support two different stories at once. A 322% increase in information-sector productivity since 1998 demonstrates how dramatically technology can raise output, while the corresponding 32% increase outside the sector shows how unevenly those gains have spread. The challenge for the next American economy is not simply producing more through AI, but whether those efficiency gains eventually reach the businesses, industries, and workers operating beyond the technology sector.
Artificial intelligence is changing not only which jobs may disappear, but also where new work is being created. Rystad Energy expects the United States to account for more than 40% of projected data-center growth among the 15 leading national markets. As that construction expands, Goldman Sachs Research found that construction employment exposed to data-center development increased by 216,000 since 2022, including work connected to electrical systems, cooling, construction, and facility infrastructure.
The demand extends beyond the buildings themselves because data centers require large amounts of reliable electricity. Goldman Sachs estimates that roughly 500,000 net new jobs will need to be filled by 2030 to meet rising U.S. power demand, including skilled trades and technical occupations rather than only data-center construction workers. The estimate is a projection, but it shows how growth in computing can create labor demand across power generation, transmission, engineering, and construction.
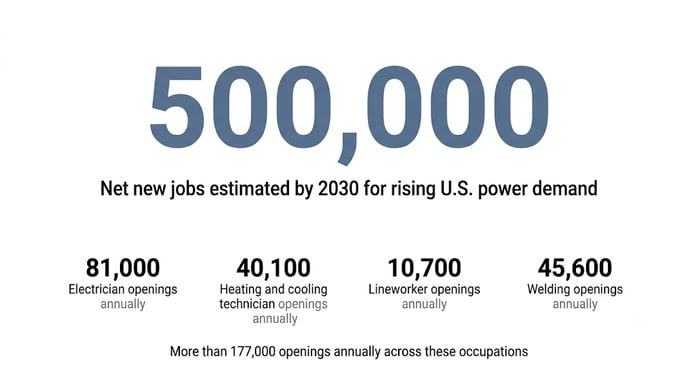
Power growth could require 500,000 new workers by 2030. Created via Gemini.
The number of openings across several infrastructure occupations is already substantial. The U.S. Bureau of Labor Statistics projects about 81,000 electrician openings, 40,100 heating and cooling technician openings, 10,700 lineworker openings, and 45,600 welding openings each year from 2024 through 2034. Together, those occupations represent more than 177,000 openings annually, illustrating the scale of the workforce pipeline needed even before every planned AI facility is built.
Those openings cannot be filled as quickly as a company can announce a new data center. Most electrician apprenticeships require about 4 to 5 years, while lineworkers and heating, ventilation, and air conditioning (HVAC) technicians also need technical instruction and extended on-the-job training. That time gap matters because a shortage of qualified workers can slow construction even when investment, land, and demand are already available.
The shift also complicates the idea that workers displaced by AI can simply move into the jobs AI creates. A worker leaving an office-based occupation cannot immediately become a licensed electrician, grid engineer, or experienced lineworker, particularly when some training paths take 4 to 5 years. The opportunity is therefore real, but reaching it depends on whether apprenticeship programs, community colleges, employers, unions, and technical schools can expand quickly enough to connect workers with the new demand.
For families deciding what kinds of careers may remain valuable in a technology-heavy economy, the numbers broaden the picture beyond four-year technology degrees. More than 177,000 projected annual openings across just four skilled occupations show that the infrastructure behind AI also depends on workers who build, wire, cool, repair, and maintain physical systems. The next challenge is ensuring that training capacity grows alongside investment so these jobs become accessible career paths rather than positions employers struggle to fill.
Artificial intelligence may feel digital to users, but the economy supporting it is increasingly physical. Data centers need electricity, transmission lines, fiber connections, cooling systems, construction crews, and local approvals before computing capacity can come online. At the Energy Imperatives Summit, one expert estimated that the United States holds only a 6 to 7 month lead over China in frontier AI capability, making that an expert assessment rather than a fixed measure of national advantage.
The timelines for building that physical capacity can be dramatically longer than the technology cycle itself. New interstate electricity transmission can take 5, 10, or even 15 years to permit, while the United States operates through 66 balancing authorities, regional organizations responsible for keeping electricity supply and demand in balance. A technology advantage measured in months can therefore run into an infrastructure system that often moves in years.
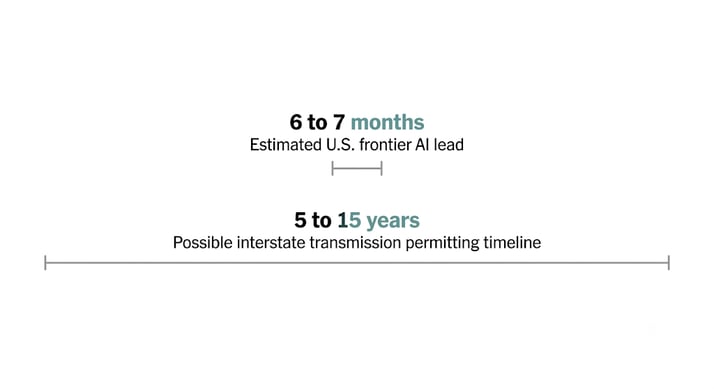
Transmission delays can outlast an AI lead. Created via Gemini.
The buildout is already supporting substantial skilled-trade employment. Meta says it operates 32 data centers globally, including 28 in the United States across 23 states, and that its data-center projects have supported about 45,000 skilled-trade roles since 2011. Those roles include the electricians, plumbers, fiber technicians, construction workers, and other specialists needed to turn planned computing capacity into operating infrastructure.
Training capacity is now becoming part of that infrastructure challenge. Meta’s America’s Workforce Academy carries a $115 million first-year commitment and is being piloted in Louisiana, Ohio, Indiana, and Texas to train workers including electricians, plumbers, and fiber technicians. The program illustrates a broader economic requirement: large technology investments create more local opportunity when training pipelines expand alongside the projects themselves.
Building faster also raises a household question about who pays for the power infrastructure required by very large electricity users. The summit discussion described tools such as long-term commitments, minimum demand charges, exit fees, and dedicated new generation as ways to prevent ordinary utility customers from absorbing costs created by large data-center loads. The Federal Energy Regulatory Commission has also focused on speeding connections for large electricity users while addressing how those costs are allocated.
Communities therefore have more at stake than whether a data center gets built. Projects can bring jobs, tax revenue, training, and infrastructure investment, but residents also have legitimate questions about electricity bills, water use, land, noise, and whether promised economic benefits will stay local. With projects already spread across 23 U.S. states in Meta’s network alone, local trust and clear financial commitments can become part of how quickly national investment turns into functioning infrastructure.
The larger economic constraint is execution. A 6 to 7 month technology advantage means less if electricity projects can require as long as 15 years to move through permitting, while a $115 million training initiative shows that workforce capacity also requires deliberate investment. The next American economy will depend not only on who develops the strongest AI systems, but on whether the country can build the power, transmission, skills, and local agreements needed to put those systems to work.
The next American economy will not be defined simply by whether artificial intelligence creates or eliminates jobs. The deeper shift is in where work happens, which skills employers value, and how workers gain the experience needed to move into higher-level roles. Some traditional office pathways may weaken while demand grows around infrastructure, energy, construction, and skilled technical work.
Those changes will not reach every worker, business, or community equally. Technology can raise productivity while its benefits remain concentrated, and declining demand for older assets such as office buildings can create financial pressure elsewhere in the economy. The challenge is making sure economic transformation creates usable opportunities for people outside the industries receiving the largest investments.
That will require more than faster technology. Training systems must help workers move into growing occupations, electricity and transmission networks must support new investment, lenders must manage changing commercial risks, and communities must be able to share in the benefits of development. The strength of the next American economy will depend on how successfully the country connects technological progress with workers, businesses, and places that need a path into it.

AI growth is testing whether households should remain protected when electricity supplies cannot...

AI leaders are calling for universal cash payments to cushion job displacement, but the fiscal math...

AI agents that can do whole tasks are quietly erasing the first rung of the career ladder in...